


You have decided you might be ready to buy a home.
You talk with a lender, answer a few questions, and hear one of two phrases:
“You’re pre-qualified.”
or
“You’re pre-approved.”
They sound almost interchangeable.
They aren’t necessarily.
Both can be useful steps in the home-buying process, but they may represent different levels of financial review. Understanding that difference can help you know how prepared you really are before you start looking at homes—or writing an offer on one you love.
And there is another important detail:
Different lenders may use these terms differently.
Instead of focusing only on the label, buyers should understand what information the lender actually reviewed and what still needs to happen before final loan approval.
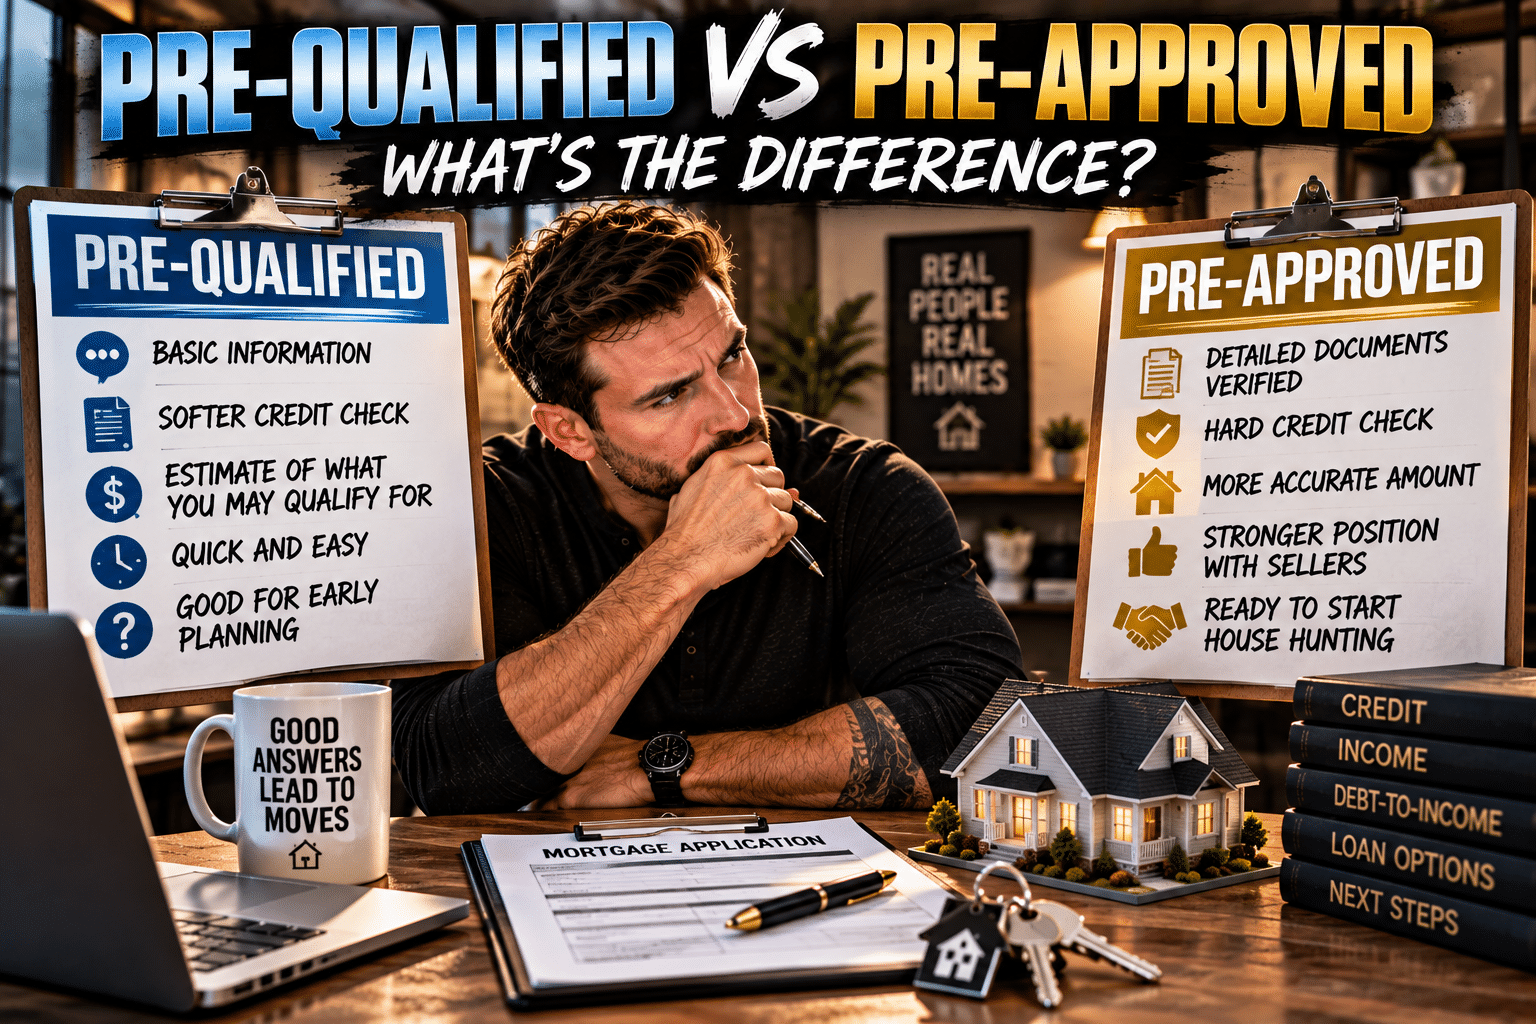
What Does Pre-Qualified Mean?
Pre-qualification is often an early step in the mortgage process.
Depending on the lender, it may be based primarily on financial information you provide, such as your income, debts, assets, estimated credit profile, and desired purchase price.
The lender may use that information to give you an estimate of the financing or price range you might qualify for.
Think of it as an initial conversation.
It can help answer questions such as:
• Does buying a home appear financially realistic right now?
• What general price range might make sense?
• What financing options may be worth exploring?
• Are there financial issues that should be addressed before moving forward?
For someone who is several months away from purchasing and simply wants to understand where they stand, that can be valuable information.
But an estimate based largely on information supplied by the borrower is different from a more detailed review of supporting financial documentation.
That is where pre-approval may come into the conversation.
What Does Pre-Approved Mean?
A mortgage pre-approval generally involves a more detailed evaluation of a prospective borrower’s financial situation.
Depending on the lender and loan program, this process may involve reviewing documentation related to areas such as:
• Income
• Employment
• Assets
• Debts
• Credit history
• Other financial obligations
The exact documents, credit review, terminology, and process can vary by lender.
After reviewing the information required for its process, a lender may issue a pre-approval indicating the amount and loan structure for which the buyer appears to qualify, subject to the lender’s conditions and further review.
That last part matters.
A pre-approval is not the same thing as final mortgage approval.
The eventual loan can still depend on the property, appraisal, title-related matters, updated borrower information, underwriting requirements, and other conditions associated with the transaction.
Still, completing a more detailed financial review before shopping can give a buyer a clearer understanding of their purchasing position.
Why Buyers Sometimes Confuse the Two
The confusion is understandable because there is no single universal process every mortgage company uses for these terms.
One lender may call an initial review a pre-qualification.
Another may have a more detailed process before using that term.
Likewise, the documentation required for a pre-approval can vary.
That is why one of the best questions you can ask a lender is:
“What did you actually review to determine this?”
That question can be more useful than the terminology printed across the top of the letter.
Ask whether the lender has reviewed your income documentation, assets, debts, credit, and other information relevant to your financing.
The more you understand about what has already been reviewed, the better you can understand where you are in the process.
Why This Matters Before You Start Looking at Homes
Looking at homes is the fun part.
Financing paperwork?
Usually not the part people post on Instagram.
But doing the financial work first can make the home search considerably more productive.
Imagine spending several weekends looking at homes around a certain price.
You find one you love.
Then you speak with a lender in greater detail and discover that your comfortable financing range is different from what you expected.
Now you may have fallen in love with a house before knowing whether the numbers work.
Getting your financing information organized early can help you build your search around a more realistic price range from the beginning.
Your Maximum Approval Shouldn’t Automatically Become Your Budget
This is another important distinction.
Even if a lender pre-approves you up to a certain amount, that does not mean you are required to spend that much.
Qualification and personal affordability are not exactly the same thing.
Your lender evaluates your finances according to lending requirements.
You still have to decide what monthly housing expense fits comfortably into your life.
You may want room in your budget for:
• Savings
• Travel
• Childcare or family expenses
• Vehicle expenses
• Retirement contributions
• Hobbies and entertainment
• Home maintenance
• Unexpected expenses
If you are pre-approved for a certain purchase amount but would be much more comfortable buying below it, tell your REALTOR®.
Your home search should be based on the number that works for you—not simply the highest number available.
A Pre-Approval Can Help You Shop More Efficiently
Once you have a clearer understanding of your financing, your REALTOR® can build a more focused home search.
Instead of looking at everything that catches your eye, you can concentrate on properties that better align with your financing and personal budget.
That allows the conversation to shift from:
“Can I afford this?”
to questions like:
“Does this home fit my needs?”
“How does it compare with other properties?”
“Does the location work for me?”
“What condition is the property in?”
“What terms would matter if I decided to make an offer?”
Those are much better questions to be asking while house hunting.
Does a Pre-Approval Make Your Offer Stronger?
A seller evaluating an offer may consider several factors, including price, financing, contingencies, timing, and other contract terms.
Evidence that a buyer has already communicated with a lender and undergone an appropriate financial review can provide useful information about the buyer’s financing preparation.
However, sellers and their representatives evaluate offers individually, and a pre-approval does not guarantee that an offer will be accepted.
It also does not guarantee that financing will ultimately close.
The strongest offer is not automatically the offer with the highest price or the buyer with a particular type of letter.
Real estate contracts contain multiple terms, and sellers may weigh those terms differently depending on their circumstances.
Pre-Approval Is Still Not Final Approval
This deserves repeating because it is one of the biggest misunderstandings buyers can have.
Pre-approved does not mean your mortgage is finished.
Once you are under contract on a specific property, there are additional steps.
Depending on the transaction and financing, those may include:
• Providing updated financial documentation
• Additional lender review or underwriting
• Property appraisal
• Title-related work
• Verification of required information
• Satisfying loan conditions
• Final approval before closing
The property itself matters too.
A lender is not simply evaluating the borrower. The lender may also have requirements related to the property being financed.
That is why a pre-approval should be viewed as an important step in the process—not the finish line.
Don’t Make Major Financial Changes Without Talking to Your Lender
Once you begin the mortgage process, consistency can matter.
Before making significant financial changes, talk with your lender about how they could affect your financing.
Examples may include:
• Financing a vehicle
• Opening new credit accounts
• Making large purchases using credit
• Changing employment
• Moving significant amounts of money between accounts
• Taking on additional debt
That does not mean you cannot live your life while buying a house.
It means this probably is not the ideal time to finance a new truck, open three store credit cards, and furnish a house you have not closed on yet.
Your lender can tell you whether a particular financial decision could affect your loan.
When in doubt, ask before making the change.
What Should You Ask Your Lender?
Whether the document says “pre-qualified” or “pre-approved,” ask questions.
A good starting conversation might include:
- What financial information have you reviewed so far?
- What documentation have you verified?
- Is there anything else you need from me before I begin making offers?
- What loan programs may fit my situation?
- What estimated monthly payment range am I looking at?
- What should I expect for cash needed during the transaction?
- How long is the information in my letter considered current?
- What financial changes should I avoid while purchasing?
- What still needs to happen before final loan approval?
You do not need to become a mortgage expert.
You just need to understand where you stand.
What If You’re Not Ready for Pre-Approval Yet?
That is okay.
Talking to a lender does not obligate you to buy a house.
In fact, having the conversation early may be useful precisely because you are not ready yet.
Maybe you need to improve your credit.
Maybe you want to reduce debt.
Maybe you need additional savings.
Maybe the payment at your desired price range is higher than you are comfortable with.
Finding that out six months before you want to buy gives you time to work on it.
Finding it out after you have already fallen in love with a house is a much less enjoyable experience.
If you are not ready today, the goal becomes building a plan for when you are.
Start With Financing, Then Start House Hunting
There is nothing wrong with browsing homes online before talking to a lender.
We all do it.
You look at one house, then another, and suddenly it is midnight and you are emotionally attached to a kitchen on the other side of town.
But when you become serious about purchasing, getting the financing conversation started early can save time and uncertainty.
Talk with a qualified lender.
Understand what they have reviewed.
Determine a monthly payment and purchase range that you are comfortable with.
Then your REALTOR® can help you turn those numbers into an actual home search.
If you are considering buying in Clarksville, Montgomery County, Cheatham County, or surrounding Middle Tennessee communities, I can help you understand the real estate side of the process and coordinate your home search with the financing information provided by your lender.
Pre-qualification can help you start the conversation. Pre-approval can provide a more detailed picture. But understanding what your lender has actually reviewed is what helps you know how prepared you really are.
This article is for general informational purposes and is not financial, legal, tax, credit, or lending advice. Mortgage terminology, underwriting procedures, credit inquiries, documentation requirements, loan programs, qualification standards, and pre-approval processes vary by lender and may change. Buyers should verify their individual financing status, current requirements, and loan options directly with an appropriately qualified mortgage professional.






