


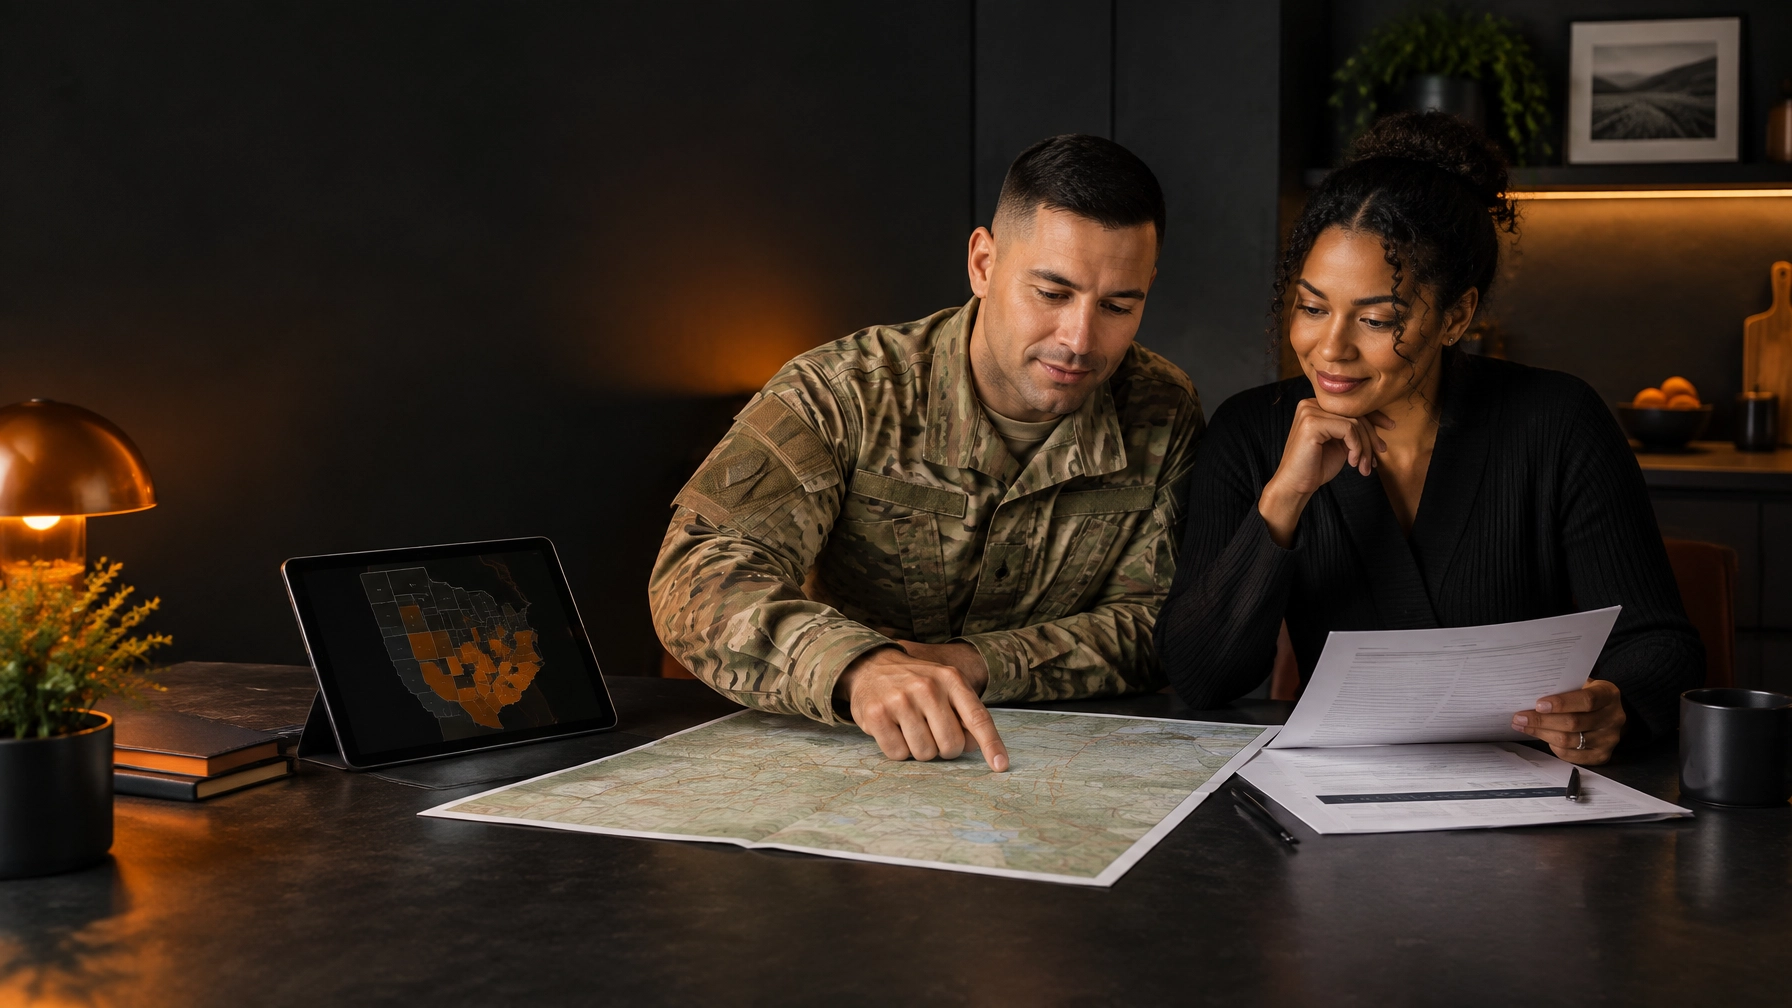
If you are buying a home near Fort Campbell, a USDA loan may be worth considering, especially if you are comparing rural or semi-rural properties in Christian County, Kentucky, or Stewart County, Tennessee.
However, USDA eligibility is not determined by the county name, city, or ZIP code alone. The exact property address must be reviewed using the official USDA eligibility map, and your household income must be checked against the current USDA limits for the applicable county and household size.
That means you should not assume that a home qualifies, or does not qualify, until a qualified lender verifies the address and your financial information.
Can you use a USDA loan in Christian County, KY or Stewart County, TN?
Potentially, yes. A USDA Guaranteed or Direct loan may be available for a qualifying primary residence in an eligible rural area of Christian County or Stewart County.
The important word is potentially. USDA property eligibility is address-specific. A home a few miles outside a city may have a different result from a home inside a more densely developed area. Even nearby properties can require separate verification.
Before making an offer, ask your lender to:
- Select the correct USDA loan program.
- Enter the property’s complete address into the official USDA Eligibility Site.
- Confirm whether the specific address meets the property-location requirements.
- Review your adjusted household income and household size.
- Confirm that the home meets the program’s property and occupancy rules.
Do not rely on a ZIP code search, a real estate listing label, or a third-party USDA map as the final determination.

What is the difference between a USDA Guaranteed loan and a USDA Direct loan?
USDA has two primary single-family housing programs. They serve different borrower groups and have different application processes.
USDA Guaranteed loan
The USDA Guaranteed Loan Program is offered through approved private lenders. The lender underwrites your application, while USDA guarantees a portion of the loan to reduce the lender’s risk.
Common features include:
- Financing that may cover up to 100% of the appraised value or eligible purchase price, subject to program and lender rules
- A primary-residence requirement
- Property-location eligibility through USDA
- An adjusted household-income limit generally tied to the moderate-income limit for the county
- Credit, debt-to-income, and repayment requirements determined by the lender and USDA guidelines
- An upfront guarantee fee and annual guarantee fee
For fiscal year 2026, USDA program guidance identifies a 1% upfront guarantee fee and a 0.35% annual fee for the Guaranteed program. The upfront fee may generally be financed into the loan when permitted. The annual fee is typically collected through the monthly mortgage payment.
For example, a 1% upfront fee on a $300,000 base loan would be approximately $3,000 before considering how the fee is financed. An annual fee of 0.35% on a $300,000 balance would begin at roughly $1,050 per year, or approximately $87.50 per month, although the actual payment calculation changes as the loan balance declines.
Confirm the current fee structure and your final payment with an approved lender. Fees and underwriting requirements can change.
You can review program information through the official USDA Single Family Housing Guaranteed Loan Program page.
USDA Direct loan
The Section 502 Direct Home Loan Program is administered directly by USDA Rural Development rather than through a conventional private lender.
It is intended for very-low- and low-income applicants who:
- Meet the applicable county and household-size income limits
- Need adequate, safe, and sanitary housing
- Are unable to obtain affordable credit through other reasonable sources
- Plan to occupy the property as their primary residence
- Purchase a modest home in an eligible rural area
A USDA Direct loan does not use the same guarantee fee structure as the Guaranteed program. Eligible borrowers may receive payment assistance based on household income and financial circumstances.
The Direct program has stricter income and eligibility requirements, so it is important to compare it with other financing options early. Visit the official USDA Single Family Housing Direct Home Loans page for current requirements.
How are USDA income limits determined?
USDA income eligibility is not based only on the income of the people signing the mortgage. The program generally reviews income for adult household members, applies allowable deductions, and considers the household’s size and the county where the property is located.
For a USDA Guaranteed loan, the household generally must fall within the applicable moderate-income limit, commonly described as no more than 115% of area median income under USDA’s methodology.
For a USDA Direct loan, the income threshold is lower and is based on the applicable low-income limit for the county and household size.
Your lender will need to review items such as:
- Wages and salary
- Military pay and allowances
- Bonuses and commissions
- Self-employment income
- Retirement or pension income
- Child support or other recurring income
- Household members who may not be borrowers
- Allowable deductions and adjustments
Do not rely on a national income example or an online lender chart for your final answer. The official limit can vary by state, county, household size, and loan program.
Ask your lender to verify your adjusted annual household income using the current USDA eligibility tools and underwriting requirements.
What does the USDA eligibility map show?
The USDA map is used to evaluate whether a specific property is located in an eligible rural area. It does not approve your loan, determine your income eligibility, or replace lender underwriting.
When reviewing a home near Fort Campbell, make sure the lender checks the exact address, not just the city, county, or ZIP code.
Your lender should also confirm:
- Whether the correct USDA map and loan program were selected
- Whether the home will be your primary residence
- Whether the property is a suitable single-family residence
- Whether acreage, outbuildings, access, utilities, or other property features create additional questions
- Whether the appraisal and inspection satisfy lender and USDA requirements
A property may be located in a county where USDA financing is commonly used but still require address-level review. Conversely, you should not reject a property solely because a general map or listing description is unclear.
How does USDA compare with VA and FHA?

USDA versus VA
A VA loan may be a natural first option for many active-duty service members, veterans, and eligible surviving spouses near Fort Campbell.
Compared with USDA, VA financing:
- Does not require the property to be in a USDA-defined rural area
- Requires military-service eligibility and a Certificate of Eligibility
- Is intended for a primary residence
- May allow no down payment for eligible borrowers with sufficient entitlement
- Does not require monthly private mortgage insurance
- May include a VA funding fee unless the borrower qualifies for an exemption
A VA-approved lender can evaluate your entitlement, service history, credit, income, occupancy plan, and property eligibility. Haus also provides additional information in its guide to VA loan requirements for Clarksville and Fort Campbell buyers.
USDA versus FHA
FHA financing does not have USDA’s rural-area or USDA household-income restrictions. It may be used for eligible primary residences in urban, suburban, and rural communities.
FHA loans commonly involve:
- A down payment requirement that may be lower than conventional financing
- Mortgage insurance premiums
- FHA appraisal and property-condition requirements
- Lender-specific credit and debt guidelines
USDA may offer an attractive low-cash-to-close structure for an eligible rural property, while FHA may provide greater location flexibility. The right option depends on your income, credit profile, cash reserves, military eligibility, property location, and long-term plans.
What about mortgage rates?
Freddie Mac’s Primary Mortgage Market Survey reported a 30-year fixed-rate average of 7.03% for the week ending September 24, 2026. This is a national benchmark, not a personal quote or a guaranteed USDA, VA, or FHA rate.
Your actual rate and payment may differ based on:
- Loan program
- Credit profile
- Loan amount
- Down payment
- Debt-to-income ratio
- Discount points
- Lender pricing
- Property type and location
- Lock period
You can review the Freddie Mac PMMS national mortgage-rate information, then ask your lender for a written Loan Estimate based on your specific circumstances.
What should Fort Campbell buyers do next?
If you are considering Christian County, Kentucky, or Stewart County, Tennessee, use this process:
- Get pre-approved. Ask a lender to compare USDA Guaranteed, USDA Direct, VA, FHA, and conventional options.
- Confirm your income category. Provide complete household income information and ask for the applicable county and household-size limit.
- Verify every property address. Use the official USDA map before treating a home as USDA-eligible.
- Review the full payment. Include principal, interest, taxes, insurance, guarantee fees or mortgage insurance, utilities, and maintenance.
- Inspect the property carefully. Rural homes may involve private wells, septic systems, longer driveways, acreage, or other systems that require additional review.
- Plan around your PCS timeline. Compare commute time, school assignment, gate access, resale considerations, and the length of time you expect to remain in the area.
For relocation planning, review Haus’s Fort Campbell PCS housing guide.

Connect with a local Fort Campbell-area buyer team
A USDA loan may be a strong fit for some buyers in Christian County or Stewart County, but eligibility must be confirmed property by property and borrower by borrower.
Haus – CVILLE Tennessee can help you compare communities, evaluate commute and property considerations, coordinate showings, and connect you with lending professionals for pre-approval. When you are ready, contact Haus to discuss your home-buying goals and connect with the Fort Campbell PCS housing resources.
This article is for general educational purposes and is not lending, legal, tax, or financial advice. USDA property eligibility, income limits, fees, lender requirements, and program rules may change. Confirm the specific address on the official USDA eligibility map and verify your income limits, fees, and financing terms with a qualified lender before making an offer.






