


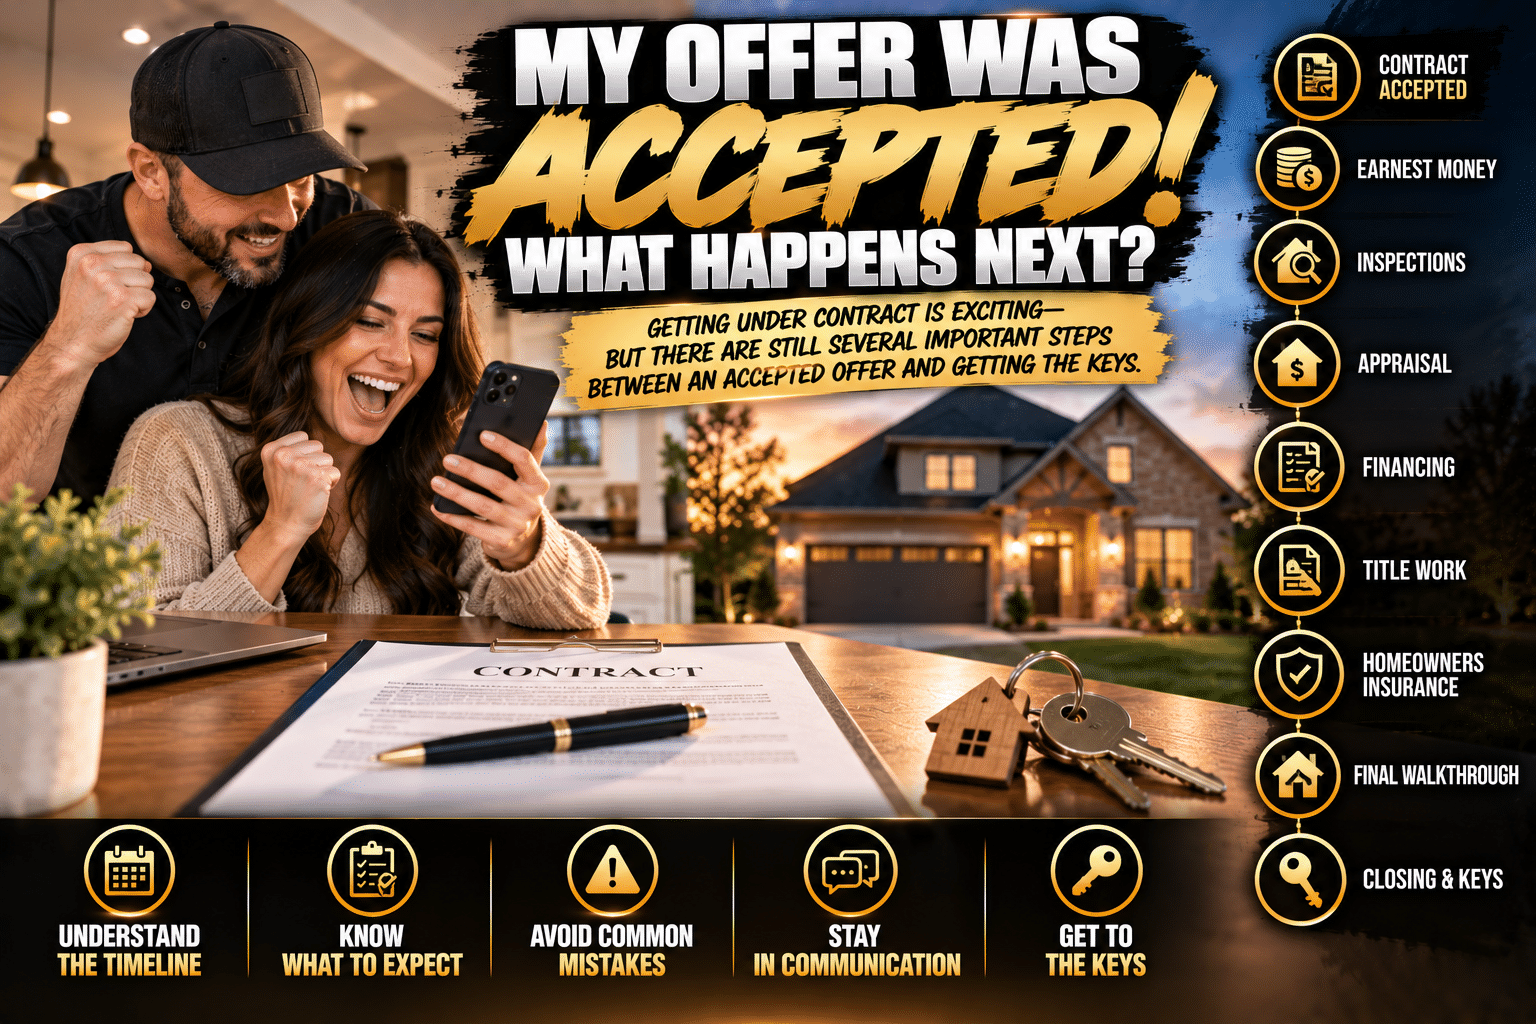
My Offer Was Accepted! What Happens Next?
“Congratulations—your offer was accepted!”
You celebrate.
Maybe screenshot the message and send it to your family.
Start thinking about where the couch is going.
Maybe you’ve already mentally claimed one of the bedrooms as your office.
And then about 30 seconds later…
“Wait. What happens now?”
Getting an offer accepted is a huge milestone, but you don’t own the house yet.
You’re officially under contract, and there are still several important steps between that accepted offer and getting the keys.
If you’re a first-time homebuyer, this part of the process can feel especially confusing because suddenly there are inspectors, lenders, appraisers, title companies, insurance agents, documents and deadlines all moving at the same time.
So let’s slow it down.
Here’s what the journey from accepted offer to closing day may look like.
Step 1: You’re Under Contract
Once the parties have reached an agreement and the contract has been properly executed, you’ve entered the next phase of the transaction.
This is where the purchase agreement becomes incredibly important.
Your contract establishes things such as the agreed purchase price, closing date and other negotiated terms and contingencies.
It may also establish deadlines involving inspections, financing, earnest money and other obligations.
Those dates matter.
A lot.
There’s no universal timeline that applies to every transaction, so don’t rely on something your friend tells you happened when they bought their house three years ago.
Follow your contract.
Your REALTOR® should help you keep track of the real-estate-related deadlines and responsibilities throughout the transaction.
Step 2: Earnest Money
Depending on the terms of your purchase agreement, you may be required to deliver earnest money.
Think of earnest money as money provided in connection with your offer that demonstrates your intention to move forward with the transaction.
The amount, deadline, holder of the funds and treatment of earnest money are governed by the applicable agreement and circumstances.
This isn’t a deadline to casually miss.
If your contract requires earnest money, make sure you know:
How much is due?
Who receives it?
When is it due?
What method of payment is acceptable?
And please verify wiring or payment instructions through trusted channels before sending money.
Real-estate wire fraud is a legitimate concern, so never blindly trust unexpected payment instructions received by email or text.
Step 3: Schedule Your Home Inspection
If your purchase agreement provides for an inspection period and you’ve chosen to conduct inspections, this part usually begins quickly.
A professional home inspector evaluates accessible components and systems of the property and provides information about their observed condition.
The inspection isn’t about trying to prove the house is terrible.
It’s about understanding what you’re preparing to own.
Maybe the inspector finds mostly routine maintenance items.
Maybe something needs further evaluation by a specialist.
Maybe something significant is discovered.
The important thing is to understand the findings and then understand what options your purchase agreement provides.
And remember:
An inspection report isn’t a pass-or-fail test.
Every house will eventually require maintenance.
What matters is understanding the nature and significance of what was discovered.
Step 4: Decide What to Do With the Inspection Results
Depending on your contract and the results of the inspection, there may be decisions to make.
The specific options available to you depend on the terms you’ve negotiated.
That could involve accepting the property as it is, requesting certain repairs or another resolution, seeking additional evaluations, or exercising another contractual option if applicable.
This is also where deadlines become extremely important.
Don’t receive an inspection report and then leave it sitting in your inbox for several days because you’re busy.
Your contractual timeline keeps moving.
Review the findings, ask questions and make decisions within the time provided by your agreement.
Step 5: Keep Your Lender Moving
While you’re dealing with inspections, your lender isn’t sitting around waiting.
The financing side of the transaction is moving too.
Expect your lender to request documents.
Potentially a lot of them.
Depending on your situation, that might include updated bank statements, pay stubs, tax documents, employment information, explanations of certain transactions or other financial documentation.
If your lender asks for something, don’t panic.
And don’t ignore the email for a week either.
Responding promptly can help keep the process moving.
There may also be documents you’ve already provided that the lender requests again in updated form.
Yes, you may occasionally think:
“Didn’t I already send them this?”
You probably did.
Send the updated document anyway.
Step 6: The Appraisal
If you’re financing the purchase, an appraisal may be required as part of the lending process.
And here’s an important distinction:
An appraisal and a home inspection are not the same thing.
The home inspection primarily helps you better understand the property’s condition.
The appraisal is primarily part of the lender’s process of evaluating the property in connection with the loan.
The appraiser develops an opinion of value using appropriate appraisal methods and market information.
Depending on the loan program, the property may also need to satisfy certain requirements.
If the appraisal supports the transaction as structured, great—the process keeps moving.
If it creates an issue, your REALTOR® and lender can help explain what happens next based on the contract, loan program and circumstances.
Step 7: Title Work Is Happening Behind the Scenes
While you’re picking apart an inspection report and sending your lender another bank statement, another important part of the transaction is happening behind the scenes.
Title work.
The appropriate title or closing professionals will research the property’s title and work through the requirements necessary for the transaction.
The goal is to identify issues that could affect ownership or transfer of the property and prepare for closing.
You may not see everything happening during this stage.
That’s normal.
A lot of real estate happens behind the curtain.
Step 8: Get Homeowners Insurance Lined Up
Don’t wait until the night before closing to think about homeowners insurance.
Your lender will generally require appropriate insurance coverage when financing a home, and getting quotes earlier can also help you understand another part of your anticipated housing expense.
Insurance cost can vary significantly based on the property and buyer’s circumstances.
Certain property characteristics or prior claims associated with a home may also affect insurance availability or cost.
So this is another area where earlier is usually better than:
“Hey, I close tomorrow. Can you insure this?”
Work with a properly licensed insurance professional to understand coverage and pricing.
Step 9: The Loan Moves Through Underwriting
At some point you may hear a word that makes first-time buyers nervous:
Underwriting.
Underwriting is essentially the lender’s detailed review of the loan file to determine whether the borrower and transaction satisfy applicable lending requirements.
The underwriter may review things such as your income, assets, debts, credit profile, property information, appraisal and documentation.
They may also request additional information or clarification.
That doesn’t automatically mean something is wrong.
Additional documentation requests can be a normal part of the process.
Just stay responsive.
VERY IMPORTANT: Don’t Make Major Financial Changes While You’re Under Contract
This deserves its own section.
Between contract acceptance and closing, your financial situation matters.
This is generally not the time to celebrate buying a house by financing $12,000 worth of furniture for the house you don’t own yet.
Before making significant financial or employment changes, talk with your lender.
That includes things such as:
- Opening new credit accounts
- Financing furniture or appliances
- Buying or leasing a vehicle
- Taking out another loan
- Co-signing debt for someone else
- Making unusually large purchases
- Moving significant amounts of money between accounts without documentation
- Making large cash deposits that may be difficult to document
- Changing jobs or employment structure
- Closing existing credit accounts
Some changes may be completely manageable.
Others could affect your loan qualification or create additional documentation requirements.
The important thing is:
Don’t surprise your lender.
If you’re thinking about making a financial move while you’re under contract, ask first.
The new sectional can wait.
Step 10: Keep Your Money Traceable
Your lender may need to verify where funds used in the transaction came from.
That’s why moving money around randomly during the mortgage process can create headaches.
If you’re receiving gift funds, transferring money, selling an asset or moving funds between accounts, ask your lender what documentation they’ll need before doing it.
And this is definitely not the time to suddenly deposit a shoebox full of cash you’ve been saving for eight years without discussing it with them.
The mortgage process loves documentation.
If money moves, there may need to be a paper trail.
Step 11: Review Your Closing Information
As closing approaches, you’ll begin receiving important information concerning the final transaction.
For financed purchases subject to applicable federal requirements, buyers generally receive a Closing Disclosure containing important information about the mortgage loan and closing costs.
Review your documents.
Don’t just scroll to the bottom looking for the number you need to bring.
Look at the loan terms.
Look at the costs.
Ask questions if something doesn’t make sense.
Closing day should not be the first time you discover something you don’t understand about your loan.
Your lender and closing professionals can help explain the appropriate portions of the transaction.
Step 12: The Final Walkthrough
You’re almost there.
Before closing, buyers commonly have an opportunity—when provided by their contract—to perform a final walkthrough.
This isn’t another full home inspection.
The purpose is generally to verify the property’s condition relative to the contractual expectations, including matters such as agreed repairs when applicable and whether the property remains in the expected condition.
This is when you’re checking things such as:
Is the house still here?
That’s a good start.
But more seriously:
Has the property’s condition materially changed?
Have agreed-upon items been removed?
Are items that were supposed to remain still there?
Were applicable agreed repairs addressed as required?
Did anything significant happen since the last time you saw the property?
If something isn’t right, tell your REALTOR®.
Step 13: Closing Day
This is the day everybody has been waiting for.
You’ll review and sign the required closing documents and complete the remaining requirements for the transaction.
The exact closing process can vary depending on the transaction and closing professionals involved.
Bring whatever identification and documentation your closing professional instructs you to bring.
And if you’re bringing or wiring funds:
Verify instructions directly with the appropriate closing professional using a trusted contact method.
Never rely solely on an unexpected email telling you that wiring instructions have changed.
And Then…The Keys
This is the part that makes everything else worth it.
The searching.
The showings.
The offer.
The negotiations.
The inspection.
The lender asking for another document.
And another document.
And somehow another version of the document you already sent twice.
Eventually you reach the moment when the transaction is complete and you’re entitled to possession according to the terms of your agreement.
Now it’s home.
The Biggest Mistake Buyers Make After Their Offer Is Accepted
They mentally check out.
Getting the offer accepted feels like such a major victory that it’s easy to think:
“We got the house!”
You’re close.
But there is still work to do.
The period between contract and closing requires communication and attention to deadlines.
Check your email.
Answer your phone.
Respond to your lender.
Stay in communication with your REALTOR®.
Complete required paperwork.
Don’t make major financial changes without speaking to your lender.
Ask questions when something doesn’t make sense.
You don’t have to become a real-estate expert overnight.
That’s what the professionals involved in the transaction are there for.
Your Job Isn’t to Know Everything—It’s to Stay Engaged
Buying a home involves a lot of moving pieces.
Your REALTOR® is working on the real-estate side.
Your lender is working on financing.
Your inspector is evaluating the property.
The appraiser has their role.
The title and closing professionals have theirs.
Insurance professionals have theirs.
And you are the person all of those pieces ultimately come together for.
So don’t feel embarrassed asking questions.
You aren’t supposed to know everything about a process most people only go through a handful of times in their lives.
A good question is much easier to deal with than a bad assumption.
From “Offer Accepted” to “Welcome Home”
Getting your offer accepted is absolutely worth celebrating.
Just understand that it’s a milestone—not the finish line.
There are still inspections to consider.
Deadlines to meet.
Financing to complete.
Documents to provide.
An appraisal may need to happen.
Title work needs to be completed.
Insurance needs to be arranged.
The final walkthrough needs to happen.
And then finally…
Closing day.
The process can look overwhelming when you see everything written out at once.
But you don’t have to tackle everything at once.
You handle the next step.
Then the next one.
Then the next one.
Until eventually someone hands you the keys.
If you’re buying a home in Clarksville or Middle Tennessee, my job isn’t just to help you find a house and write an offer.
It’s to help you understand what happens after the offer gets accepted, too.
Because real estate can be complicated.
Getting good information should never be.
— Jamie Taylor, REALTOR®
Your Tennessee Homes Team
Haus Realty & Management
Serving Clarksville & Middle Tennessee
This article is provided for general educational purposes and is not legal, lending, financial, tax, insurance, appraisal or inspection advice. Contract terms, contingencies, earnest-money requirements, inspection rights, financing requirements, deadlines, possession and closing procedures vary by transaction. Buyers should rely on their specific purchase agreement and consult the appropriate licensed professionals regarding their individual circumstances.






