


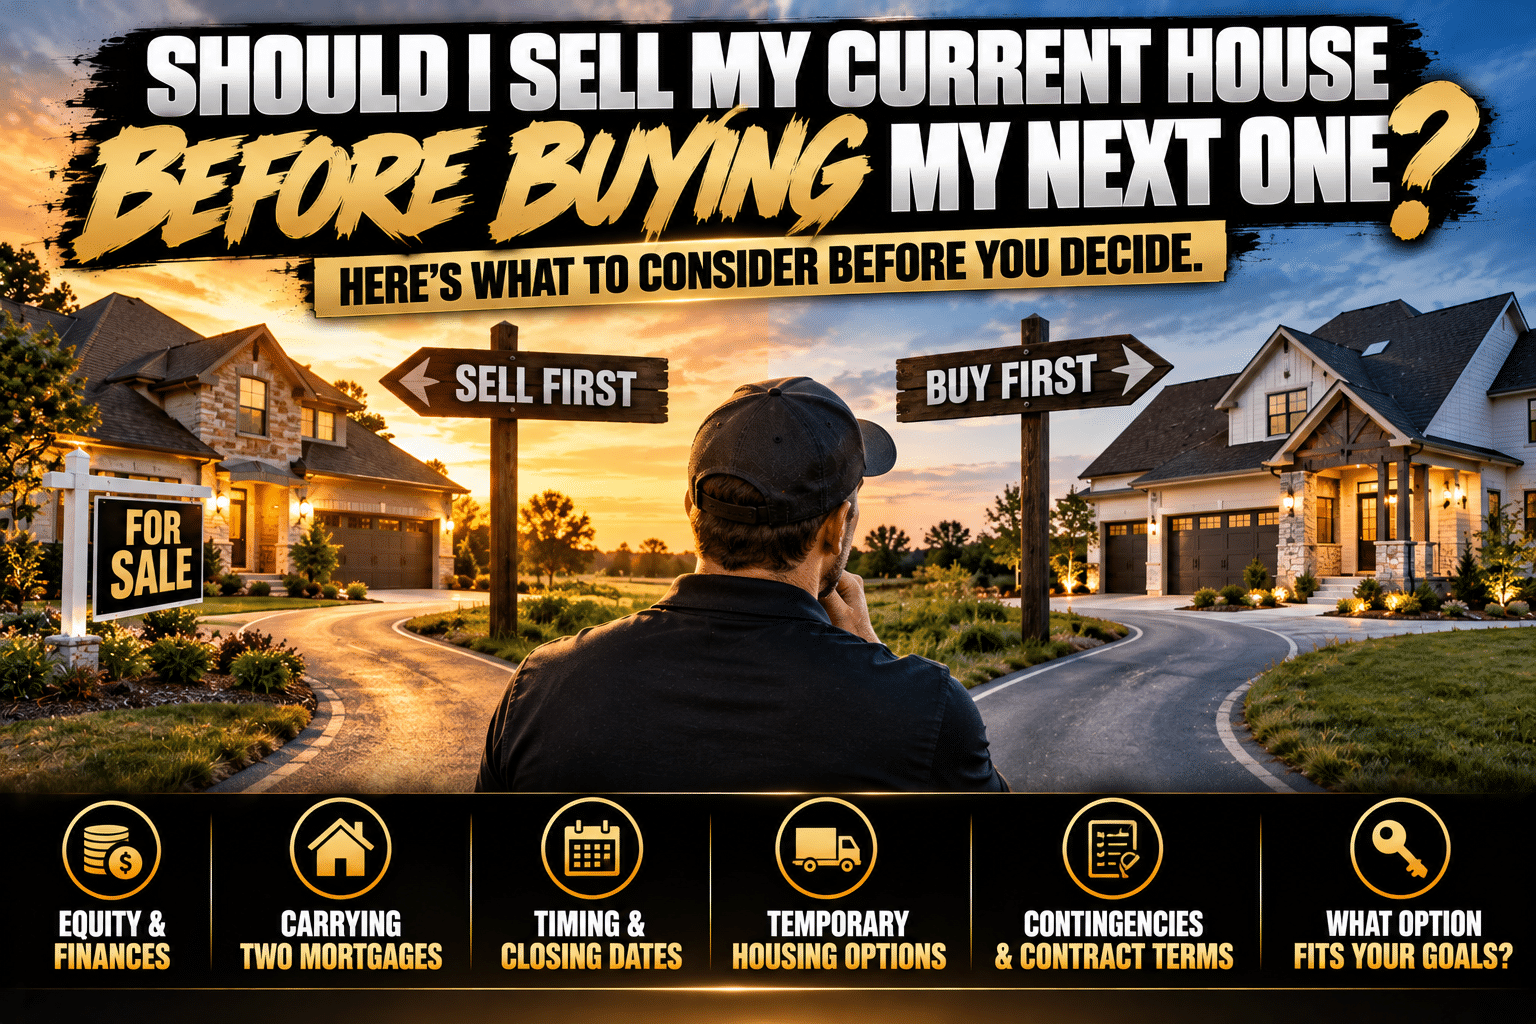
Should I Sell My Current House Before Buying My Next One?
You’ve decided you’re ready for another home.
Maybe you need more space.
Maybe you want less space.
Maybe you’re relocating, changing school districts, shortening a commute, or you’re simply ready for something different.
There’s just one problem:
You already own a house.
And now you’re staring at the real-estate version of the chicken-or-the-egg question:
Do I sell this house first—or buy the next one first?
It’s one of the most common questions homeowners face when they’re ready to move.
And unfortunately, there isn’t one answer that works for everyone.
Selling first can make the financial side of your next purchase much simpler—but it can create pressure to find somewhere else to live.
Buying first can make the physical move much easier—but potentially creates financial risk if your current home doesn’t sell as quickly as expected.
So rather than asking which option is universally “better,” there’s a more useful question:
Which risk are you better prepared to manage?
Let’s break it down.
Option #1: Sell Your Current Home First
For many homeowners, a significant portion of the money they plan to use toward their next home is currently sitting in one place:
Their existing home’s equity.
If you sell first, that equity may become available to use toward the next purchase after the sale closes and applicable mortgage balances, transaction expenses and other obligations are paid.
That can potentially make the next purchase financially easier to structure.
But selling first creates another problem.
You still need somewhere to live.
The Advantages of Selling First
Selling your current home before purchasing another may offer several benefits.
You may:
- Know how much money you’re actually receiving from your sale.
- Have access to proceeds from the sale for your next purchase.
- Avoid owning two homes at the same time.
- Reduce uncertainty surrounding whether your current home will sell.
- Potentially make an offer on the next property without needing the sale of your current home to occur first.
That last point can matter.
An offer that depends on another property selling introduces another moving piece into the transaction.
Depending on market conditions and the seller you’re negotiating with, that may affect how your offer is viewed.
But selling first isn’t automatically the easy option.
The Biggest Problem With Selling First: Where Do You Go?
Let’s say everything goes perfectly.
Your house hits the market.
You receive an offer.
You negotiate the contract.
You make it through inspections, appraisal and closing.
Congratulations.
You sold your house.
There’s just one tiny detail:
You haven’t bought another one yet.
Now you may need temporary housing.
That could mean:
- Renting temporarily
- Staying with family
- Using short-term accommodations
- Putting belongings into storage
- Moving twice
And moving once is already enough fun for most people.
Moving everything into storage and then moving it all again three weeks later isn’t exactly anyone’s dream Saturday.
There may be ways to coordinate possession or closing dates depending on the transaction, but those arrangements require agreement between the parties and should never simply be assumed.
Option #2: Buy Your Next Home First
Now let’s flip it around.
Instead of selling first, you find the next house, purchase it and then sell your current property.
From a moving standpoint?
That can be fantastic.
You have somewhere to go.
You may be able to move at your own pace.
You don’t necessarily have to coordinate two moving trucks, a storage unit and your mother-in-law’s guest bedroom.
You can potentially prepare the old house for market after moving out.
Sounds perfect.
Until we get to the financial side.
Can You Actually Afford to Own Both Homes?
This is one of the first conversations you should have with a qualified lender before deciding to buy first.
Being able to afford the down payment on another property is only one part of the equation.
Depending on your circumstances and financing, your lender may need to consider your existing mortgage obligation when determining your ability to qualify for the next loan.
There may also be a period when you’re responsible for expenses associated with both properties.
Potentially:
Two mortgage payments.
Two sets of utilities.
Two insurance obligations.
Two homes requiring maintenance.
And your current house doesn’t automatically sell the moment you close on the new one.
Maybe it sells immediately.
Maybe it takes longer.
You need to understand what happens financially if the second scenario occurs.
Don’t Build the Plan Around the Best-Case Scenario
This is where I encourage homeowners to be realistic.
If your entire plan only works if:
“My house sells immediately.”
Then we need to examine that plan carefully.
Instead ask:
What happens if it takes 30 days?
60 days?
Longer?
What if a buyer’s transaction falls apart?
What if an inspection leads to additional negotiations?
What if an appraisal creates an issue?
What if the market changes?
That doesn’t mean any of those things will happen.
It means your plan should have enough breathing room that one unexpected event doesn’t create a financial emergency.
Hope for the smooth transaction. Plan for the imperfect one.
Your Equity May Be the Deciding Factor
For many homeowners, this is where the decision starts becoming clearer.
Imagine you own a home worth substantially more than what you currently owe.
That’s great.
You have equity.
But equity and cash aren’t necessarily the same thing.
Until the home is sold—or you use an appropriate financial product that allows you to access qualifying equity—that money is generally still tied to the property.
If you planned to use proceeds from your current home for the down payment and closing expenses on the next one, buying first may require a different strategy.
That’s why the conversation shouldn’t begin with Zillow.
It should begin with the numbers.
What could your current home realistically sell for?
Approximately how much do you owe?
What might your estimated net proceeds look like after the transaction?
How much cash do you have available outside of the property?
What does your lender say you can qualify for while still owning the current home?
Those answers can dramatically change the strategy.
Option #3: Make Your Purchase Contingent on Selling Your Current Home
There’s also a middle-ground strategy.
Depending on the market, property and seller, a buyer may submit an offer that includes a contingency related to selling their existing home.
Essentially, the buyer’s purchase of the new property is connected to the sale of their current property under the terms negotiated in the contract.
This can help address some of the financial risk of buying first.
But there’s a tradeoff.
The seller of the home you want is being asked to accept uncertainty tied to another transaction.
They aren’t only waiting for you to close.
They’re potentially waiting for the buyer of your house to close too.
That doesn’t automatically make a contingent offer bad.
But its strength depends on the circumstances, market conditions and terms involved.
This is one of those areas where offer structure matters just as much as offer price.
Could You Coordinate Both Closings?
Sometimes, yes.
It’s possible for homeowners to structure transactions where the sale of their existing property and purchase of the next property happen very close together.
Sometimes even on the same day.
When everything lines up, it’s beautiful.
Sell one.
Buy the other.
Move.
Done.
But there are a lot of moving pieces.
Your sale has its own:
Buyer.
Lender.
Inspection.
Appraisal.
Title work.
Underwriting.
Closing.
And your purchase has another entire set of those pieces.
If something changes on one side, it can potentially affect the other.
So while coordinated closings can work very well, timing should be planned carefully and backup plans matter.
What About Temporary Occupancy After Closing?
In some transactions, a seller may negotiate an arrangement allowing them to remain in the property for an agreed period after closing.
You may hear this called a temporary occupancy arrangement, seller possession after closing, rent-back, or similar terminology depending on the documents and circumstances involved.
This can sometimes help bridge the gap between selling one property and moving into another.
But it isn’t automatic.
It requires agreement between the parties and creates additional considerations involving possession, liability, insurance, deposits, payments, property condition and other terms.
If something like this is part of the strategy, make sure it’s properly documented and that you understand the agreement.
There May Be Financing Strategies Too
Depending on your financial situation and available loan products, a lender may be able to discuss financing options designed to help homeowners transition between properties.
The important word there is:
Lender.
Your REALTOR® can help you evaluate the real estate side of the transaction, estimated proceeds, timing, offer structure and market conditions.
A qualified mortgage professional should explain the financing products for which you may qualify and how those options affect your particular situation.
Don’t build an entire buy-before-you-sell strategy around a financing product you haven’t actually discussed with a lender.
Market Conditions Matter
The strategy that makes sense in one market may not make sense in another.
If homes similar to yours are selling quickly while you’re shopping in an area with plenty of available inventory, the equation may look one way.
If your current property may require more time to sell while the homes you want are receiving heavy competition, the equation may look completely different.
That’s why generic internet advice can only take you so far.
Your strategy should consider both sides of your move.
Not just:
“What can I buy?”
But also:
“What am I selling?”
Your Current Home’s Condition Matters Too
Ask yourself how much work your existing property needs before it’s ready for market.
If you buy first and move out, preparing the old home may become easier.
You can paint without furniture in the way.
Clean without working around daily life.
Handle repairs.
Stage rooms differently.
Keep the house ready for showings without getting a text saying:
“Can we show it in 30 minutes?”
while you’re standing in the kitchen looking at breakfast dishes and wondering how fast a human being can vacuum an entire house.
On the other hand, carrying another property while preparing and marketing the first one costs money.
Convenience and financial efficiency aren’t always the same thing.
Your Personal Stress Level Matters More Than You Think
This part doesn’t show up on a mortgage calculator.
Some people are financially comfortable buying first but absolutely hate the idea of carrying two houses.
Others would rather carry two properties temporarily than sell first and feel pressured to choose their next home quickly.
Neither person is wrong.
Think about what would bother you more:
Owning two homes temporarily?
Or:
Selling yours and not knowing exactly where you’re going next?
Real estate decisions aren’t made in a spreadsheet alone.
The strategy also has to work for your actual life.
So…Which One Should You Do?
Here’s the frustrating answer:
It depends.
But that’s actually good news.
You don’t need a universal rule.
You need a plan built around your situation.
Before deciding, I would want a homeowner to understand at least:
- The realistic market value of their current home
- Their approximate mortgage payoff
- Estimated selling expenses and potential net proceeds
- How much equity they may have available
- Their available cash outside the property
- What a lender says they can qualify for
- Whether they could comfortably carry both homes
- Current market conditions for the home they’re selling
- Current market conditions for the type of home they’re buying
- How flexible they are with timing and temporary housing
- How much financial and logistical risk they’re comfortable accepting
Once you have those answers, the decision usually becomes much easier to evaluate.
Don’t Start With “Sell First or Buy First?”
Start with:
“What would each option look like for me?”
Let’s run the numbers.
Let’s look at your current house.
Let’s estimate what selling it might realistically look like.
Let’s talk with a lender about the purchasing side.
Then let’s build Plan A.
And preferably Plan B.
Because the best real estate strategy isn’t the one that sounds easiest on paper.
It’s the one that still works when everything doesn’t happen perfectly.
If you’re in Clarksville or Middle Tennessee and you’re thinking about selling your current home and buying another, you don’t have to figure out the order by yourself.
We can start by looking at the numbers and your options before you ever put a sign in the yard or make an offer on another property.
No pressure to list.
No pressure to buy.
Just figure out what the move would actually look like first.
— Jamie Taylor, REALTOR®
Your Tennessee Homes Team
Haus Realty & Management
Serving Clarksville & Middle Tennessee
This article is provided for general educational purposes and is not legal, lending, tax, financial, or insurance advice. Financing options, qualification requirements, contingencies, possession arrangements, contract terms, costs and available strategies vary by transaction and individual circumstances. Buyers and sellers should consult the appropriate licensed professionals regarding their specific situation.






