


Getting approved for a mortgage is exciting. You finally have a number, you open the home search, and suddenly houses that were just pictures online start feeling like real possibilities.
But before you set your search price at the very top of that approval amount, there is another question worth asking:
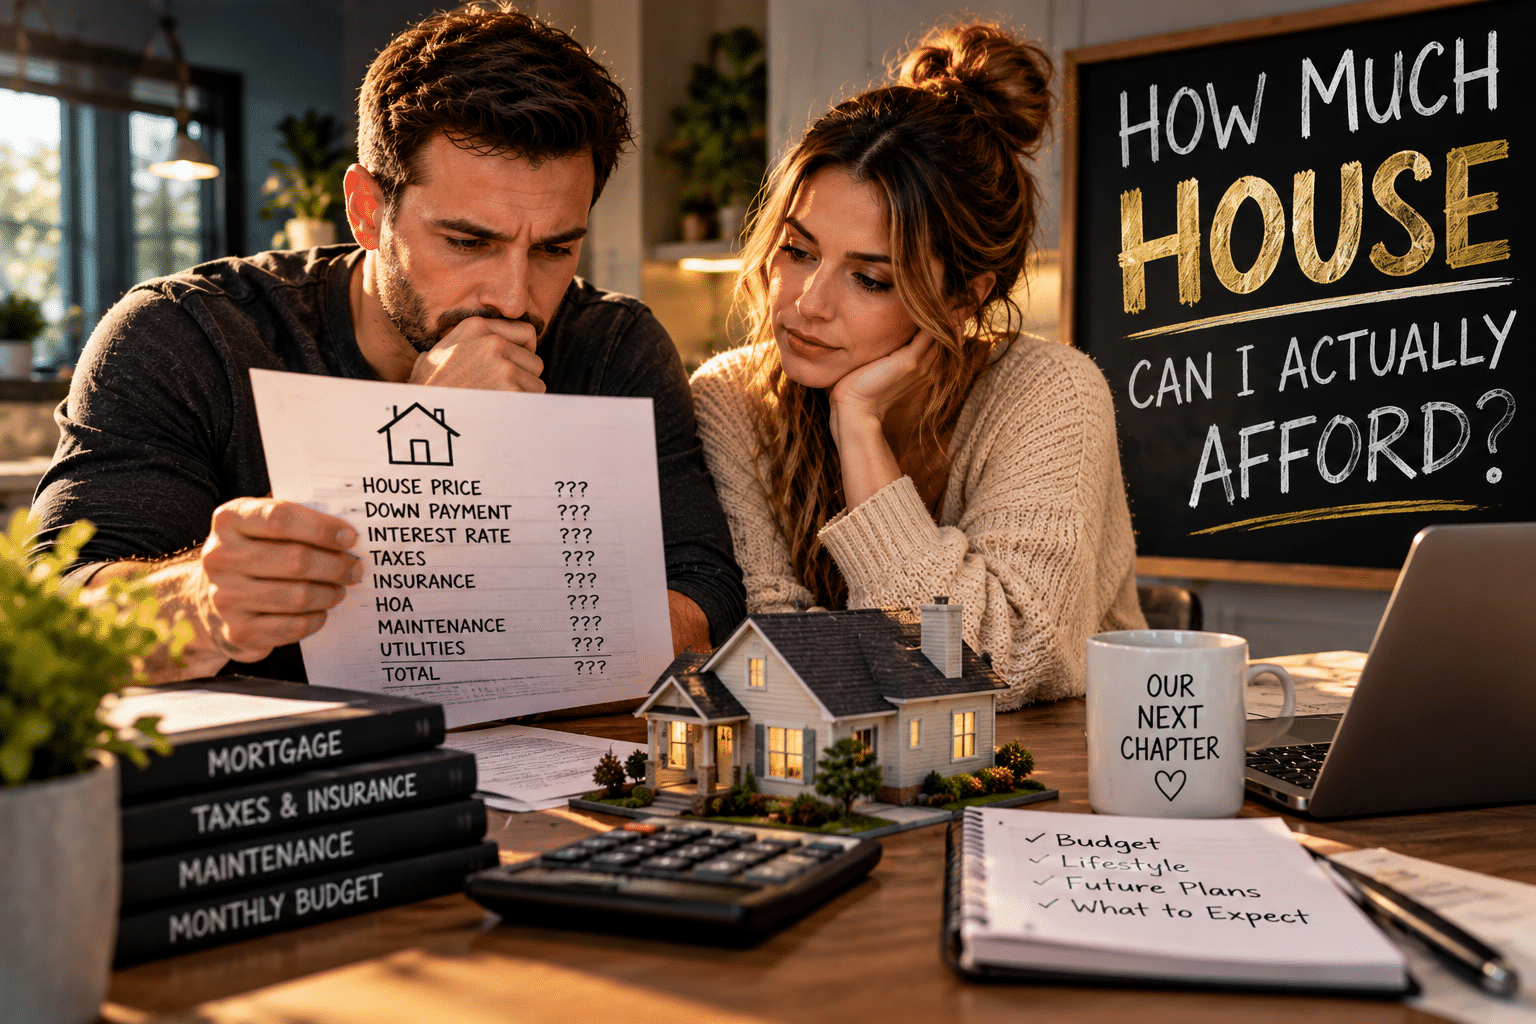
How much house can I comfortably afford?
Those two numbers are not always the same.
A lender can help determine what you may qualify to borrow based on your financial situation and the loan program. Your personal budget, however, has to account for something a calculator cannot fully understand—your actual life.
The goal should not simply be buying the most expensive house you can qualify for. It should be finding a home you love with a payment that still allows you to enjoy your life after closing.
Start With the Payment, Not Just the Purchase Price
When buyers search for homes, the natural tendency is to focus on price.
“I’m approved up to $400,000, so let’s look at houses up to $400,000.”
But the purchase price alone does not tell you what owning that home will cost each month.
Your housing expenses may include:
• Principal and interest
• Property taxes
• Homeowners insurance
• Mortgage insurance, when applicable
• Homeowners association fees, when applicable
• Utilities
• Routine maintenance and repairs
The exact expenses will vary depending on the property and financing.
That is why two homes with the same purchase price do not necessarily create the same monthly financial picture.
Instead of beginning with, “What is the highest-priced house I can buy?” consider beginning with:
“What monthly housing expense am I comfortable living with?”
That conversation can completely change how you approach your home search.
What You Qualify For and What You Want to Spend Are Different Questions
Mortgage qualification is based on financial criteria. Personal comfort is based on your life.
A lender does not decide how much you like traveling, how often you eat out, how aggressively you want to save for retirement, whether you have children involved in activities, or whether you simply enjoy having extra breathing room in your checking account.
Those things matter.
Imagine two buyers with similar incomes and debts who qualify for similar mortgage amounts.
One buyer may be perfectly comfortable spending toward the upper end of that range because housing is a major priority and their other expenses are relatively low.
The other may prefer a lower payment because they travel frequently, have significant childcare expenses, are building a business, or simply value having more disposable income.
Neither buyer is necessarily making the wrong decision.
Affordability is personal.
Remember the Expenses That Come After Closing
Closing day gets plenty of attention, but homeownership continues the next morning.
Eventually, something will need attention.
An appliance may stop working. The HVAC system will require maintenance. A fence may need repair. A room may need paint. The yard still needs to be maintained, and apparently grass refuses to respect your monthly budget.
Welcome to homeownership.
These expenses do not mean buying a home is a bad financial decision. They simply need to be considered before purchasing.
If your mortgage payment consumes so much of your budget that every unexpected repair becomes a financial emergency, you may have purchased more house than is comfortable for your situation.
Leaving room in your budget for maintenance, savings, and unexpected expenses can make homeownership considerably less stressful.
Your Down Payment Is Not the Only Cash to Consider
Another common mistake is focusing exclusively on the down payment.
Depending on the transaction and financing, buyers may also need to account for expenses such as closing costs, inspections, appraisal-related expenses, moving costs, deposits, immediate repairs, furnishings, and other costs associated with getting settled.
Some expenses may be negotiable or handled differently depending on the transaction, loan program, and market conditions.
That is why it is important to speak with your lender and REALTOR® early in the process rather than relying solely on an online mortgage calculator.
The question is not simply:
“Do I have enough money to close?”
It is also:
“What will my finances look like after I close?”
Don’t Empty Your Savings Just to Reach a Certain Price Point
Buying a home is a major financial milestone, but closing day should not necessarily leave your bank account running on fumes.
Keeping appropriate savings available after purchasing can provide a cushion for repairs, moving expenses, emergencies, and normal life.
Maybe stretching your budget allows you to buy the larger house.
But if buying slightly below your maximum allows you to keep more savings, furnish the home comfortably, handle unexpected repairs, and sleep better at night, that can be valuable too.
There is no universal percentage or dollar amount that every buyer should keep in reserve. Your financial situation is individual, and a qualified financial or lending professional can help you evaluate it.
The important part is simply remembering that buying the house is not the finish line for your finances.
Think About the Life You Want Outside the House
This is one of the most overlooked parts of determining affordability.
Picture yourself six months after closing.
You love the house.
But can you still do the other things that matter to you?
Can you take a vacation?
Go out to dinner?
Save money?
Handle a vehicle repair?
Put your kids in activities?
Enjoy a weekend without mentally calculating how many days remain until payday?
A beautiful home should improve your lifestyle—not make you afraid to leave it because you spent the entertainment budget on the mortgage.
When setting a comfortable price range, think beyond bedrooms, bathrooms, and square footage.
Think about the life that payment needs to support.
A Lower Purchase Price Doesn’t Mean Settling
There can be a strange psychological effect once buyers receive a pre-approval.
If you are approved up to a certain amount, it can suddenly feel like spending less means getting less.
That is not necessarily true.
A home below your maximum budget might provide:
• More financial flexibility
• Additional savings after closing
• Room for future improvements
• Less pressure from the monthly payment
• More flexibility when unexpected expenses occur
The goal is not to spend your entire approval.
The goal is to find the right combination of home, location, payment, and lifestyle.
Sometimes that house happens to be near the top of your range.
Sometimes it does not.
Online Mortgage Calculators Are a Starting Point
Online calculators can be helpful when you are beginning to explore homeownership.
They can give you a rough idea of how different purchase prices, down payments, and interest rates may affect a payment.
But they should not be treated as a final answer.
Taxes, insurance, financing terms, mortgage insurance, association fees, and other property-specific expenses can significantly affect the actual numbers.
A qualified lender can provide financing information based on your individual circumstances.
Once you have that information, your REALTOR® can help structure a home search around the properties and price range that make sense for you.
That combination is much more useful than simply typing numbers into an online calculator and hoping for the best.
Before You Start Shopping, Answer These Questions
Before deciding on your home-search price range, consider asking yourself:
- What total monthly housing expense feels comfortable to me?
- How much money do I want left over each month after my normal expenses?
- How much savings do I want available after closing?
- What expenses or lifestyle priorities am I unwilling to sacrifice for a house?
- Could I comfortably handle an unexpected home repair?
- Do I expect any major financial or lifestyle changes in the next few years?
- Am I choosing this price range because it works for me—or simply because I was approved for it?
Those answers can help turn a pre-approval amount into a realistic home-buying strategy.
Buy the Home You Can Enjoy Owning
There is nothing wrong with buying toward the upper end of your budget when the numbers make sense.
There is also nothing wrong with buying well below it.
The important thing is understanding the difference between being able to purchase a home and being comfortable owning it.
Your lender can help you understand your financing options and qualification. Your REALTOR® can help you understand what different price ranges may offer in the areas where you want to live.
Then you get to make the most important decision:
What payment and purchase price make sense for your life?
If you are considering buying in Clarksville, Montgomery County, Cheatham County, or surrounding Middle Tennessee communities, I can help you understand what your budget may look like in the actual housing market and build a home search around your priorities—not simply the maximum number on a pre-approval letter.
Because getting the keys is exciting.
Being able to comfortably enjoy the home after you get them is even better.
This article is for general informational purposes and is not financial, legal, tax, or lending advice. Mortgage rates, loan programs, qualification requirements, taxes, insurance costs, and other expenses can change. Buyers should verify financing information and individual affordability with the appropriate qualified professionals before making a real estate decision.






