


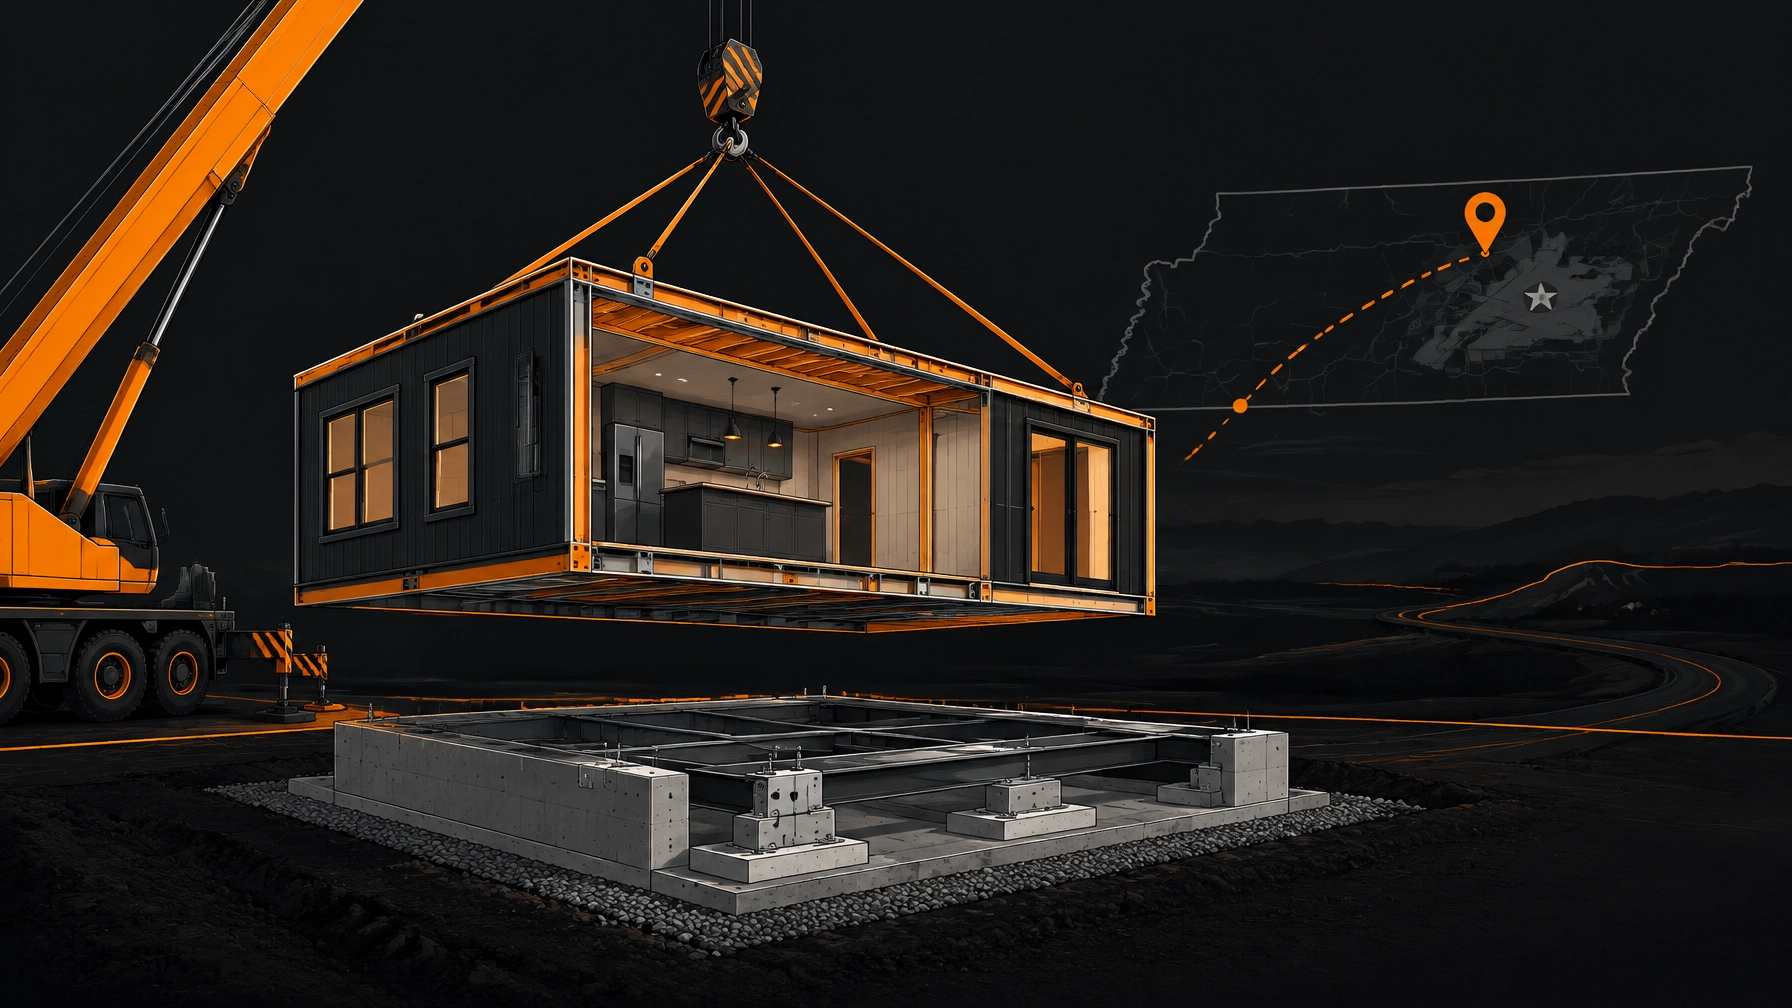
Buying a modular or off-frame home near Fort Campbell starts with confirming what kind of home you are buying and whether the land is included. A true modular home is generally built to the applicable state and local building code and installed on a permanent foundation, so it may be financed much like a site-built home. A manufactured home is built to federal HUD code; it may be titled as personal property unless it is properly converted to real property under the rules where it sits.
That distinction can affect your loan options, taxes, insurance, and eventual resale. Before you make an offer or pay a dealer deposit, confirm the home’s construction code, title status, foundation plan, and land ownership. Those first checks are especially important for buyers considering Clarksville, Tennessee, or Oak Grove and Hopkinsville, Kentucky.
Modular vs. Manufactured vs. Off-Frame: What’s the Difference?
“Off-frame” is often used in sales conversations to describe a manufactured home installed without its transport frame, but the label alone does not establish the home’s code, title, or financing eligibility. Ask the seller or dealer for the home’s certification documents and confirm the details with your lender and the local authority.

| What to compare | Modular home | Manufactured or off-frame home |
|---|---|---|
| Construction standard | Typically state and local building codes | Federal HUD construction code |
| Foundation | Installed on a foundation designed for the home and site | Installation and permanent foundation requirements matter; “off-frame” is not proof of compliance |
| Title and classification | Often treated as real property once completed and attached to land | May begin with a separate personal-property title; conversion rules vary by state |
| Financing | May fit real-property mortgage or construction-to-permanent financing | May require real-property conversion for mortgage financing; chattel financing may also be offered |
| Taxes, insurance, and resale | Confirm local assessment and coverage with the county and insurer | Classification, title conversion, age, condition, foundation, and lender rules can affect treatment and buyer pool |
These are general distinctions, not a determination for a particular property. Tennessee’s modular program separates state-regulated modular construction from HUD-regulated manufactured homes. For any specific home, ask for the applicable code label or certification, plans, installation instructions, and title documents.
Where Can You Find Modular and Off-Frame Homes Near Fort Campbell?
Start by comparing the communities and land options that fit your commute, budget, and PCS timeline. Clarksville and the wider Montgomery County area offer a range of housing and land opportunities. In Kentucky, explore Oak Grove, Hopkinsville, and surrounding Christian County. Each property is subject to its own zoning, access, utility, and installation requirements, so don’t assume a parcel can accept the home you have in mind.
Explore Montgomery County, Tennessee and Christian County, Kentucky as you compare areas. If you’re PCSing, the Haus military relocation hub is a useful starting point for broader Fort Campbell planning.
How Do You Finance a Modular or Off-Frame Home?
First, ask a lender who regularly handles factory-built homes to review the exact model, land arrangement, foundation, and location. Find out whether you need a construction-to-permanent loan, a mortgage on a completed home and land, or a personal-property loan. Ask the lender to confirm in writing what construction code, title status, and foundation the loan requires.
Rate differences can make the loan structure especially important. Freddie Mac’s Primary Mortgage Market Survey reported national averages of 7.28% for a 30-year fixed mortgage and 6.60% for a 15-year fixed mortgage on October 1, 2026. These are dated national survey averages, not a quote for your VA loan or a manufactured-home loan. At elevated rates, the payment difference between real-property mortgage financing and a chattel or personal-property loan can matter more. Ask lenders to quote both structures, including fees, points, lock timing, and any construction-period terms.
Budget for the full project, not just the home itself. Depending on the property and contract, costs can include land, site preparation, survey, foundation, transport, crane or set, utility connections, septic or well work, permits, driveway, inspections, and finish work. Get itemized estimates from the responsible providers before you commit.
Can You Use a VA Loan on a Modular or Off-Frame Home?
Possibly. The VA says an eligible borrower may use a purchase loan to buy a manufactured home or lot, and VA loans can also be used to build a new home. Eligibility is only one part of approval: you must meet VA and lender requirements, occupy the home, and satisfy the lender’s standards for the specific property and loan structure. Review the VA purchase-loan guidance and ask a VA-experienced lender whether it will finance your specific home in the county where it will be installed.

If you plan to use BAH in your household affordability plan, check the current Fort Campbell rate using the Department of Defense’s official BAH lookup. Treat BAH as one part of your monthly budget, not as a substitute for a lender’s estimate of principal, interest, taxes, insurance, and other expenses.
What Should You Check Before Buying the Land?
Confirm with the county or relevant local office that the parcel’s zoning and restrictions allow the home type and intended use. Check legal road access, easements, setbacks, flood risk, grading and drainage, utilities, and whether a septic system or well is feasible. Ask who is responsible for permits, delivery access, foundation approval, installation inspections, and utility connections.
Before ordering, match the home’s specifications to the site and lender’s requirements. For a manufactured home, establish what steps are needed to attach it to the land and convert its title, if applicable. In Tennessee and Kentucky, titling and property classification processes differ. Confirm the procedure with the Montgomery County, Tennessee, or Christian County, Kentucky, property assessor and the appropriate local title or recording office before closing.

How Do Taxes and Insurance Differ?
Whether the home is assessed as real property or remains separately titled can influence how it is taxed and insured. The exact treatment depends on its classification, location, ownership, installation, and local procedures. Before closing, ask the county assessor how the proposed setup will be classified, and get an insurance quote using the home’s construction type, foundation, age, and intended occupancy. Don’t rely on a generic estimate for a different home or county.
What Should You Know About Resale Value?
Resale depends on more than whether a home is modular or manufactured. Buyers and lenders may consider the home’s condition, age, layout, installation quality, title, foundation, land ownership, and comparable properties. A clearly documented home that is properly attached to its land and accepted by local authorities may be easier for future buyers to evaluate. Ask your agent to review comparable sales and discuss likely resale considerations before you select a model or parcel.
Guidance for Fort Campbell Buyers
A Haus Realty & Management broker and relocation specialist notes that Haus agents routinely help Fort Campbell buyers compare modular and off-frame options in Clarksville, Tennessee, and Oak Grove and Hopkinsville, Kentucky. Two of the most important early questions are how the home is titled and whether it will sit on a permanent foundation. Getting those answers early can help you narrow the search and coordinate next steps with a lender, installer, and local officials.
Frequently Asked Questions
Is an off-frame home the same as a modular home?
Not necessarily. “Off-frame” is a sales term; confirm whether the home is state- or locally code-regulated modular construction or a HUD-code manufactured home.
Can I use a VA loan to buy a manufactured home near Fort Campbell?
VA guidance allows purchase loans for manufactured homes or lots, but lender requirements and property eligibility apply. Ask a VA-experienced lender to review the exact home, foundation, title, and county.
Can I use a VA loan for the home and the land together?
It may be possible, but the loan structure, eligible costs, construction plan, and lender program determine what can be financed. Get lender approval before signing a home or land contract.
Do I need to own the land?
Not always for every financing option, but land ownership and title treatment can affect mortgage eligibility, taxes, insurance, and resale. Confirm how the arrangement works before you commit.
What should I ask first if I’m buying during a PCS?
Ask what code the home is built to, how it will be titled, whether the foundation is permanent, whether the land is included, and whether your lender and the local jurisdiction approve the plan.
Want help comparing modular, off-frame, and site-built options near Fort Campbell? Talk with a Haus Realty & Management agent about your home search and financing structure. Contact Haus to start a conversation.






