


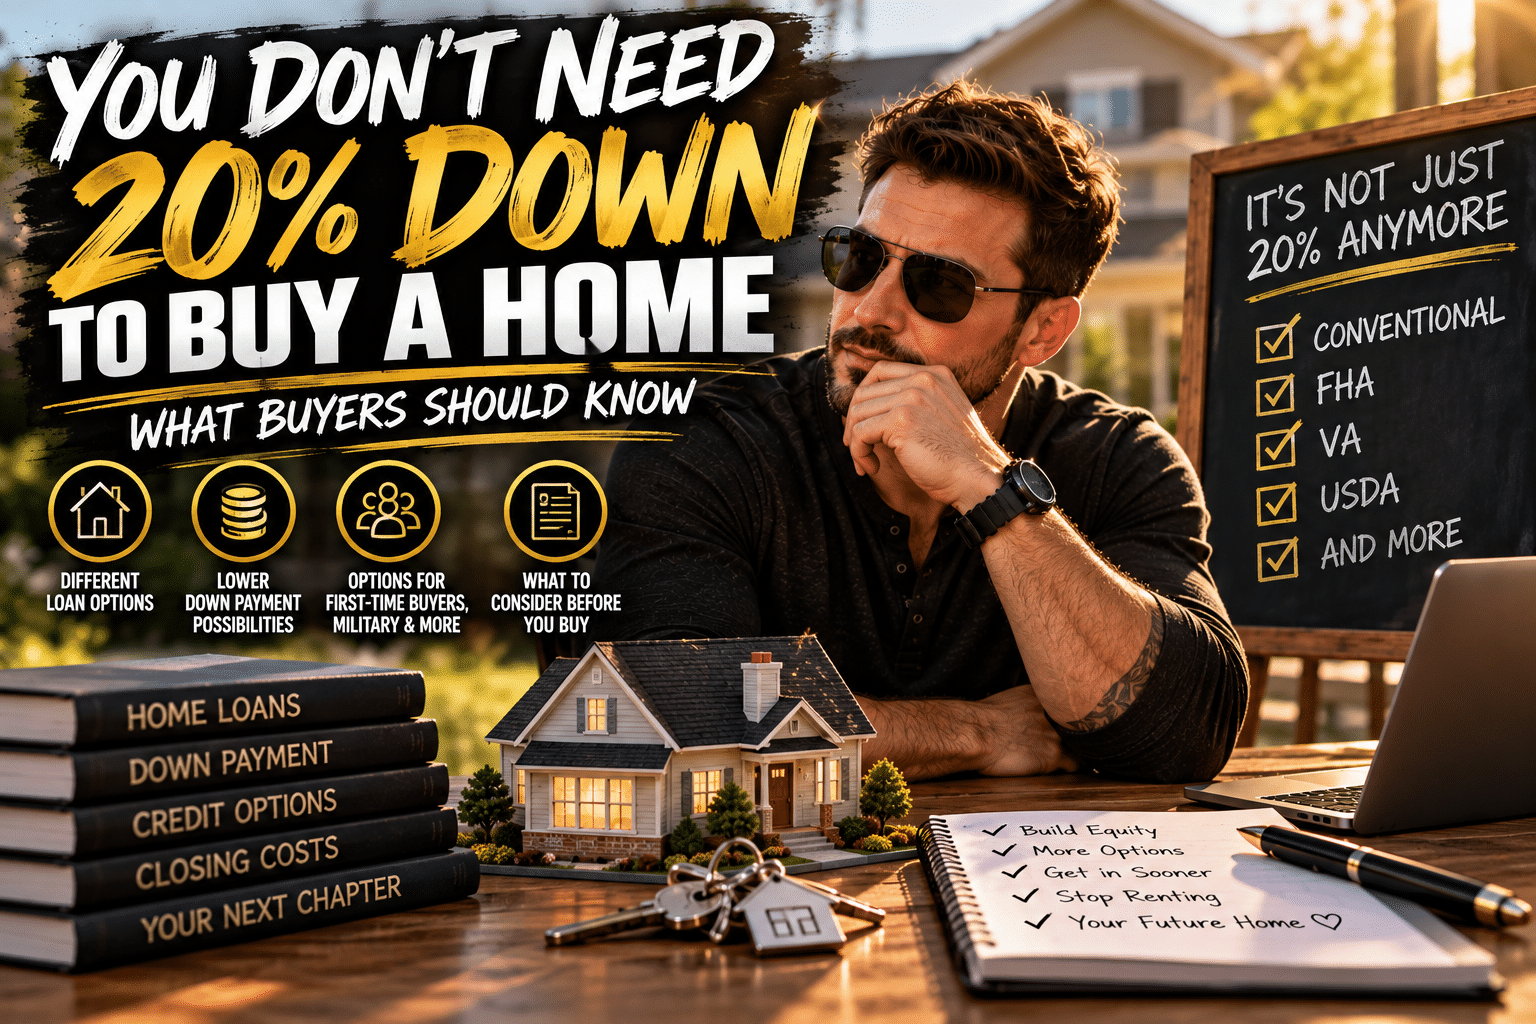
If you have been putting off buying a home because you think you need 20% of the purchase price sitting in your savings account, it may be time to take another look.
The idea that every buyer needs a 20% down payment is one of the most persistent misconceptions in real estate.
Twenty percent down may be an option, but it is not a universal requirement for buying a home.
Depending on your financial situation, eligibility, property, and loan program, there may be financing options that require considerably less money upfront.
That does not mean every buyer should automatically make the smallest down payment possible. It means you should understand your options before deciding homeownership is out of reach.
You might be closer than you think.
Where Did the 20% Down Payment Idea Come From?
There are legitimate reasons buyers hear so much about putting 20% down.
A larger down payment can reduce the amount you need to borrow and may lower your monthly principal and interest payment. Depending on the financing, it may also affect mortgage insurance requirements, loan terms, or other costs.
But somewhere along the way, “20% can have advantages” became “you need 20% to buy a house.”
Those are two very different statements.
Home financing is not one-size-fits-all. Different buyers may qualify for different programs with different down-payment structures and requirements.
Before spending years trying to reach an arbitrary savings number, find out what options actually apply to you.
There Are Different Types of Home Loans
One reason the 20% misconception can be misleading is that there is more than one way to finance a home.
Depending on eligibility and other requirements, buyers may encounter financing options such as:
• Conventional loans
• FHA loans
• VA loans
• USDA loans
• Other specialized or assistance programs
Each has its own qualification standards, costs, benefits, restrictions, and property requirements.
Some programs may allow eligible borrowers to purchase with significantly less than 20% down, while certain eligible buyers may have access to financing that does not require a traditional down payment.
That does not mean every program is appropriate or available for every buyer.
A qualified mortgage professional should evaluate your individual situation and explain the current requirements, costs, and options available to you.
A Smaller Down Payment Doesn’t Mean Buying a Home Is Free
This distinction is important.
Down payment and cash needed to purchase a home are not necessarily the same thing.
Even when a loan program allows a smaller down payment, buyers may still need funds for other expenses associated with the transaction.
Depending on the purchase and financing, those expenses could include:
• Closing costs
• Inspections
• Appraisal-related costs
• Prepaid expenses or escrow funding
• Moving expenses
• Immediate repairs or purchases after closing
Some transaction costs may potentially be negotiated or structured differently depending on the loan program, contract, property, seller, and market conditions.
The important thing is to understand the complete financial picture, not simply the down-payment percentage.
Should You Put 20% Down If You Can?
Maybe.
There is no universal answer.
For some buyers, putting more money down may make financial sense. It can reduce the amount borrowed and may affect the monthly payment and other financing costs.
For another buyer, putting every available dollar into the down payment could leave them with very little savings after closing.
Imagine having enough money available to make a large down payment—but doing so would nearly empty your savings account.
Now the HVAC needs repair three months after closing.
That larger down payment may suddenly feel a little different.
This is why the question should not simply be:
“How much can I put down?”
It should also be:
“How much should I put down while still maintaining a financial position I am comfortable with?”
That is a conversation worth having with your lender or other qualified financial professional.
Your Down Payment Can Affect Your Monthly Cost
A smaller down payment can make purchasing a home accessible sooner, but there can be tradeoffs.
Generally, borrowing more money means financing a larger portion of the purchase price. Depending on the loan, a smaller down payment may also involve mortgage insurance or other financing considerations.
A larger down payment may reduce the amount financed and change the monthly payment structure.
This is where buyers should compare actual scenarios rather than making assumptions.
Ask your lender to explain how different down-payment amounts could affect:
• Estimated monthly payment
• Cash needed at closing
• Mortgage insurance, when applicable
• Loan terms and costs
• Remaining savings after closing
Seeing those scenarios side by side can make the decision much easier to understand.
Don’t Wait Years Based on a Number You Never Verified
Suppose someone wants to buy a $350,000 home.
They believe they need 20% down, so they assume they need $70,000 just for the down payment.
They look at their savings and think:
“Well, homeownership isn’t happening anytime soon.”
But what if that buyer qualifies for a financing option with a different down-payment requirement?
Suddenly, the conversation changes.
That does not automatically mean they should buy today. Their income, credit, debts, savings, employment, monthly budget, and other factors still matter.
But now they can make the decision based on real information instead of an assumption.
That is the part I want prospective buyers to understand.
Do not eliminate yourself before you have even had the conversation.
First-Time Buyers Should Ask About Their Options
Buying your first home can feel especially intimidating because there is a lot of unfamiliar terminology.
Down payments.
Closing costs.
Pre-approvals.
Interest rates.
Mortgage insurance.
Debt-to-income ratios.
Escrow.
By the time somebody finishes explaining all of it, you may feel like you accidentally signed up for an accounting class.
You do not need to become a mortgage expert before talking to a lender or REALTOR®.
That is what the professionals involved in the transaction are there to help explain.
If you are a first-time buyer, ask what financing programs may be available based on your circumstances and whether there are legitimate assistance options for which you might qualify.
Program availability and requirements can change, so current information should always be verified with an appropriate qualified professional.
Military Buyers May Have Different Options
For eligible military buyers and veterans, VA financing can be an important option to discuss with a lender experienced with VA loans.
VA financing has features that differ from many other loan types, including its approach to down payments for qualifying borrowers.
Eligibility, property requirements, funding fees, lender requirements, and other factors can affect an individual transaction, so buyers should not assume that simply having military service automatically guarantees a particular loan structure or approval.
If you are PCS’ing to the Fort Campbell or Clarksville area, getting connected with a knowledgeable lender early can be especially helpful when you are trying to coordinate financing, housing, reporting dates, and a move at the same time.
Don’t Forget About Your Emergency Fund
There is another reason I do not like buyers becoming obsessed with reaching exactly 20%.
You still need to live after closing.
Homeownership comes with expenses.
Eventually something will break.
Something will need maintenance.
And somehow the appliance that worked perfectly during the inspection may decide it has fulfilled its life’s purpose shortly after you receive the keys.
Having money available after closing matters.
A buyer may determine that putting less money down while maintaining appropriate savings works better for their situation. Another buyer may prefer putting more down and reducing the amount financed.
Neither strategy is automatically right for everyone.
The goal is to understand the tradeoffs.
Start With Information, Not Assumptions
If buying a home is one of your goals, you do not need to wait until you have a 20% down payment before beginning the conversation.
Start by figuring out where you actually stand.
Talk with a qualified lender about:
- What loan programs you may qualify for.
- How much down those programs currently require.
- Your estimated cash needed for the overall transaction.
- How different down payments could affect your estimated monthly payment.
- Whether mortgage insurance or other costs would apply.
- How much savings you would have remaining after closing.
Then you can decide whether buying makes sense now or whether you would benefit from spending more time preparing.
Either outcome is useful.
If you are ready, you have a path forward.
If you are not ready yet, you can build a plan based on actual numbers instead of guessing.
You May Be Closer to Homeownership Than You Think
Saving money before purchasing a home is important.
But waiting until you have 20% down simply because someone told you that is “what you’re supposed to do” could cause you to postpone your plans unnecessarily.
Find out what applies to you.
Your lender can explain the financing side. Your REALTOR® can help you understand what your budget and priorities look like in the actual housing market.
If you are considering buying in Clarksville, Montgomery County, Cheatham County, or surrounding Middle Tennessee communities, I can help you understand the home-buying process and connect the pieces between your financing, home search, and individual goals.
You do not need to know everything before you start.
Sometimes the first step toward buying a home is simply finding out what is actually possible.
This article is for general informational purposes and is not financial, legal, tax, or lending advice. Loan programs, down-payment requirements, eligibility standards, mortgage insurance requirements, interest rates, assistance programs, and other financing terms can change. Buyers should verify current program requirements and their individual eligibility with an appropriately qualified mortgage professional before making a real estate decision.






